A numéraire is the thing you measure prices in. That is genuinely all it is — and it sounds so trivial that it is easy to miss why it matters.
Prices are ratios. Saying a stock is worth 100 means 100 of something, normally currency. But there is nothing special about currency. You could quote the stock in units of a money-market account, or in units of a bond maturing in five years, or in units of another stock. Each choice is a numéraire, and each one comes with its own probability measure.
The reason this is more than semantics: **choosing the right numéraire can turn a hard pricing problem into an easy one**, and the Black-Scholes formula you already know is secretly a two-numéraire statement.
The invariance that makes it work
The formal result is the change-of-numéraire theorem. For any asset  that is strictly positive and traded, there exists a measure
 under which every traded asset divided by is a martingale:
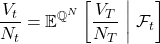
So the price today is
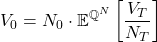
Two conditions on , both essential. It must be **strictly positive**, because you are dividing by it. And it must be **traded**, because the argument rests on being able to hold it.
The familiar case is 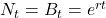 , the money-market account, which gives
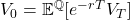 — ordinary risk-neutral pricing. That is not the definition of pricing; it is one numéraire choice among many, and often not the convenient one.
Black-Scholes contains two numéraires
Look at the formula again:
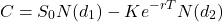
Everyone learns that  is “the probability of exercise”. Fewer people are told what
 is. Both are the probability of the same event — that the option finishes in the money — computed under two different numéraires.
With 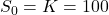 ,
 ,
 ,
 :
| Quantity | Value | What it is |
|---|---|---|
|
0.559618 |  , money-market numéraire |
|
0.636831 |  , stock numéraire |
Same event. Two measures. A difference of 7.7 percentage points.
Simulating four million paths under each measure confirms it:
| Monte Carlo | Closed form | |
|---|---|---|
|
0.559562 | 0.559618 |
|
0.636801 | 0.636831 |
The reason they differ is the drift. Under  the log-drift is
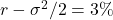 ; under
 it is
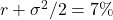 . Switching to the stock as numéraire shifts the drift up by exactly
 . Paths where the stock does well are weighted more heavily, precisely because you are now measuring everything in units of the stock, and the stock is worth more on those paths.
So the two terms in Black-Scholes are the two legs of the payoff, each valued in the numéraire that makes it simplest: the stock leg in stock units, the cash leg in cash units.
The price does not care which one you pick
That is the whole point. Pricing the same call two ways from the same random numbers:
| Numéraire | Expression | Price |
|---|---|---|
| Money market | 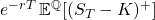 |
10.456033 |
| Stock | 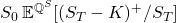 |
10.454250 |
| Black-Scholes | 10.450584 | |
Agreement to within Monte Carlo noise. Different measure, different drift, different integrand — same answer, because the price is a ratio and the numéraire cancels.
**Probabilities are measure-dependent. Prices are not.** That distinction is worth keeping, because it is the source of a lot of confusion: people ask what “the probability” of an event is when the honest answer is “under which numéraire?”
Why practitioners actually bother
The invariance means you may choose freely, so choose to make the maths disappear.
**Interest rate options.** A caplet pays at  but its rate is fixed at
 , and the discount factor is itself random — awkward under the money-market numéraire, where you have to handle the correlation between the payoff and the discounting. Switch to the -bond as numéraire and the discount factor becomes the numéraire, so it drops out. The forward rate is a martingale under that **forward measure**, and the caplet prices with the Black formula. This is the entire reason the Black-76 model works.
**Swaptions.** Use the swap annuity as numéraire and the swap rate becomes a martingale under the **swap measure**. Same trick, same payoff — a Black-style formula where a direct approach gives you a mess.
**Exchange options.** A payoff of  has two random assets. Use
 as the numéraire and it becomes
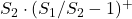 — a single-asset option on the ratio, struck at 1. That is Margrabe’s formula, and it is a Black-Scholes calculation once you have made the right choice.
**Quantos and FX.** A domestic investor and a foreign one use different numéraires, which is why they disagree about expected exchange rates while agreeing about forwards. The  quanto adjustment is precisely the density between the two.
The common pattern: **whatever is making the problem hard, try making it the numéraire.** Random discount factor, second risky asset, annuity — put it in the denominator and it stops being a problem.
Where it bites in practice
Two things that catch people out, and neither is a technicality.
**The numéraire must be traded and strictly positive.** These sound like footnotes and they are not. A rate is not a numéraire — you cannot hold 5%. A bond that can default is not a valid numéraire for the horizons where default is possible, because it can hit zero. And under a collateral agreement the relevant numéraire is the one the collateral is remunerated at, which is why a fully collateralised trade discounts on the collateral rate rather than a theoretical risk-free one.
**Probabilities quoted without a numéraire are meaningless.** If a risk report says the probability of an event is 56%, it is worth asking under which measure. and differ by nearly eight points on a plain at-the-money option; on a longer or more volatile trade the gap is much wider. Mixing them up is a real and recurring source of error, because both are “the probability of exercise” in the loose sense and only one of them is the one you wanted.
Code
import numpy as np
from scipy.stats import norm

S0, K, r, sig, T, M = 100., 100., 0.05, 0.20, 1.0, 4_000_000
rng = np.random.default_rng(9)
Z = rng.standard_normal(M)

# money-market numeraire: log-drift r - sig^2/2
ST_Q = S0*np.exp((r - 0.5*sig**2)*T + sig*np.sqrt(T)*Z)
price_Q = np.exp(-r*T)*np.maximum(ST_Q - K, 0).mean()

# stock numeraire: log-drift r + sig^2/2, and divide the payoff by S_T
ST_S = S0*np.exp((r + 0.5*sig**2)*T + sig*np.sqrt(T)*Z)
price_S = S0*np.mean(np.maximum(ST_S - K, 0)/ST_S)

print(f"money market : {price_Q:.6f}")
print(f"stock        : {price_S:.6f}")
print(f"Q(S_T>K)     = {(ST_Q > K).mean():.6f}   <- N(d2)")
print(f"Q^S(S_T>K)   = {(ST_S > K).mean():.6f}   <- N(d1)")
The test to run on any implementation: price something two ways under two numéraires. If the prices disagree by more than Monte Carlo noise, one of the drift adjustments is wrong — and that is a far sharper check than comparing a single number against a closed form you might have coded the same wrong way twice.
The takeaway
A numéraire is just the unit prices are quoted in. Any positive traded asset will do, each brings its own measure, and the price is the same under all of them — which is exactly the freedom that lets you pick whichever one makes the problem tractable.
Once you see it, and stop being two mysterious normal CDFs and become the same probability seen from two vantage points. Black-76, Margrabe, the forward measure and the quanto adjustment all turn out to be one idea applied four times.
The mechanics of the switch live in the Radon-Nikodym derivative — the density between two numéraire measures is the ratio of the numéraires — and rest on the martingale property, since a numéraire is defined by what it makes a martingale.
Change of measure, change of numéraire and the numerical checks that catch a wrong drift adjustment are worked through from the ground up in the course modules.
Get the Quant Reference Card — four pages covering stochastic calculus, measure change, the models you'll meet, discretisation, rates, credit and XVA. Free.