The standard CVA formula makes an assumption it doesn’t advertise: that your exposure to a counterparty and their probability of defaulting are independent.
Often they aren’t. And when they aren’t, the formula doesn’t fail loudly — it just returns a number that’s too small, and you find out how much too small at the worst possible moment.
That dependence is wrong-way risk. Here’s what it is, how much it costs, and what desks do about it.
The definition
Wrong-way risk is when your exposure to a counterparty increases in exactly the scenarios where that counterparty is more likely to default.
Right-way risk is the benign opposite: your exposure shrinks when their credit deteriorates.
Recall the standard CVA integral:
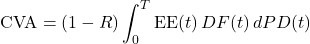
Look at what that expression does. It multiplies expected exposure by default probability, each computed separately. That product is only correct if the two are independent — because 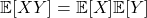 requires independence.
Wrong-way risk is precisely the failure of that assumption. And because exposure and default become positively correlated, the true expectation is larger than the product of the marginals. The formula understates.
The classic example
You’ve entered an FX forward with a corporate in an emerging market. You receive USD; they pay local currency.
If the local currency devalues sharply, two things happen at once:
- Your position moves in your favour — they now owe you more.
- Their creditworthiness collapses, because their revenues are in the currency that just devalued while their obligations are in dollars.
Your exposure and their default probability are driven by the same shock. The scenarios where you stand to lose the most are exactly the scenarios where they’re least able to pay.
Let’s price it:
import numpy as np
rng = np.random.default_rng(7)

n, T, steps = 300_000, 3.0, 36
dt = T/steps
times = np.arange(steps+1)*dt
notional, R = 5_000_000.0, 0.40

# FX rate: local currency per USD. A spike means devaluation.
fx = np.ones((n, steps+1))
for i in range(1, steps+1):
    fx[:,i] = fx[:,i-1]*np.exp(-0.5*0.20**2*dt
                               + 0.20*np.sqrt(dt)*rng.standard_normal(n))

mtm  = (fx - 1.0) * notional        # we gain when FX rises
expo = np.maximum(mtm, 0)
df   = np.exp(-0.03*times)
mid  = lambda A: 0.5*(A[:,:-1] + A[:,1:])

def cva(lam):
    surv = np.exp(-np.cumsum(lam*dt, axis=1))
    dPD  = -np.diff(surv, axis=1)
    return (1-R)*(mid(expo)*df[:-1]*dPD).sum(axis=1).mean()

lam_independent = np.full_like(fx, 0.03)          # 3% flat hazard
lam_wrongway    = 0.03*np.exp(1.5*np.log(fx))     # hazard rises with FX

print(f"CVA assuming independence: {cva(lam_independent):>10,.0f}")
print(f"CVA with wrong-way risk:   {cva(lam_wrongway):>10,.0f}")
CVA assuming independence:     22,243
CVA with wrong-way risk:       36,871
Understated by:                  1.66x
The standard formula prices this trade at 22k of credit charge. The correct number, accounting for the dependence, is 37k. **You’ve underpriced the credit risk by two-thirds**, and you’d have quoted the client accordingly.
How much it matters, as a function of correlation
The FX example uses a specific structural link. More generally, the size of the effect scales with how strongly exposure and credit are coupled:
Correlation          CVA   vs independent
       -0.6       18,136
       -0.3       27,303
       +0.0       39,290            1.00x
       +0.3       54,149            1.38x
       +0.6       71,825            1.83x
       +0.8       85,100            2.17x
At high positive correlation the charge more than doubles. And notice the other end: with correlation  , right-way risk cuts CVA to less than half. That’s not a rounding difference — ignoring the dependence can be wrong by a factor of two in either direction.
Which is worth pausing on, because right-way risk is real money too. If your exposure genuinely shrinks when the counterparty weakens, charging the independent CVA means you’re overpricing and losing trades to competitors who model it properly.
Where it shows up in practice
Wrong-way risk isn’t exotic. It’s structural in several common situations:
- Selling credit protection to someone correlated with the reference — buying CDS on a bank from another bank in the same jurisdiction. If the sector goes, the protection is worth most exactly when the seller can’t pay. This is the textbook case, and it’s roughly what happened with monoline insurers in 2008.
- FX with emerging-market corporates — the example above. Extremely common in trade finance.
- Commodity hedges with producers — an oil producer hedging by selling forward. If oil collapses, your claim against them grows and their solvency deteriorates simultaneously.
- Rates with leveraged counterparties — a highly indebted counterparty paying fixed. Rates rise, your position gains, and their debt service costs rise too.
- Collateral correlated with the counterparty — accepting a firm’s own bonds, or their equity, as collateral. When you need the collateral is exactly when it’s worthless.
That last one is a specific and dangerous case. Collateral is supposed to reduce exposure, and correlated collateral does the opposite of what the risk system thinks it does.
Modelling it
There’s no single standard approach, which itself tells you something about the difficulty.
Alpha multiplier. The blunt instrument: scale CVA by a factor above 1 to account for the dependence. Basel’s default alpha of 1.4 is essentially this. Crude, but it’s a supervisory floor rather than a model.
Correlated simulation. Simulate market and credit factors with an explicit correlation, as in the table above. Conceptually clean and the correlation is one more parameter to argue about — because it isn’t observable and can’t be calibrated to anything liquid.
Hazard rate as a function of market factors. Make the default intensity depend directly on the exposure driver, as in the FX example:  . More structural, and
 can sometimes be estimated from how the counterparty’s CDS spread has historically moved with the relevant factor.
Structural/jump-to-default models. Model the counterparty’s asset value directly, so default and market moves share a common driver by construction. Most realistic, heaviest to implement, rarely worth it outside the largest exposures.
Stress and limits. Where the dependence is structural but unquantifiable, many desks stop modelling and start restricting — refuse the trade, demand collateral in an uncorrelated asset, or cap the exposure. **Sometimes the right answer to a risk you can’t price is not to take it.**
Why it’s genuinely hard
Two reasons the industry hasn’t converged on a standard method.
First, **the correlation isn’t observable.** There’s no liquid instrument whose price tells you the correlation between your exposure and a specific counterparty’s default. You’re estimating from history, from structural reasoning, or from judgement — and in a stress, historical correlations are exactly the ones that break.
Second, **it’s a tail phenomenon.** Wrong-way risk bites in scenarios that are rare by construction. Your simulation needs enough paths in the joint tail to say anything, and that’s where Monte Carlo error is worst. You’re trying to measure precisely the region you have least data about.
The interview answer
Wrong-way risk is the dependence between exposure and counterparty default — your claim grows in the scenarios where they’re least able to pay. It matters because the standard CVA formula multiplies expected exposure by default probability, which is only valid under independence; when they’re positively correlated the formula systematically understates, easily by a factor of two.
And if pushed for an example: selling credit protection to a counterparty correlated with the reference entity, or an FX forward with an emerging-market corporate whose revenues are in the currency that just devalued.
The general point
The lesson generalises past CVA. Wrong-way risk is what happens when an independence assumption buried inside a formula turns out to be false — and independence assumptions are everywhere, usually unstated.
**Knowing which assumptions a model makes, and which of them are likely to fail in a stress, is most of what model risk management actually is.** The formula won’t tell you. You have to go looking.
If you want the machinery underneath — exposure simulation, CVA and the modelling choices that decide whether the number is defensible — that’s what we build in the modules.
Get the Quant Reference Card — four pages covering stochastic calculus, measure change, the models you’ll actually meet, discretisation, rates, credit and XVA, with the practitioner notes that don’t make it into textbooks. Free.