You buy an at-the-money call at 20% implied volatility and hedge its delta every day. At expiry the stock is back where it started, and the annualised realised volatility is 25.1%. Did you make money? You cannot tell from those numbers. Here are two trades with those exact specifications: one loses 0.63 per share, the other earns 0.30.
Same returns, different hedge
Start with a stock and strike of 100, twenty trading days to expiry, zero rates, no dividends and no costs. Buy one European call for 2.2475 per share. At each close, hedge the next day’s move using the Black–Scholes delta at the original 20% volatility. On both paths there are eighteen flat days and two consecutive daily log returns of +0.05 and −0.05. The only thing we change is when those two days occur.
| When the stock moves | Realised volatility | Gain on stock hedge | Net P&L per share |
|---|---|---|---|
| Days 1 and 2 | 25.10% | 1.6131 | −0.6344 |
| Days 19 and 20 | 25.10% | 2.5452 | +0.2977 |
Both calls expire worthless. In each case you are short stock on the way up, increase the short position at the higher price, then profit from the reversal. With one trading day left after the late rally, the call is well in the money relative to its remaining volatility: its delta is close to one. After the early rally the call still has nineteen days left and its delta changes less. You therefore carry a larger short position into the late reversal. In that case the hedge earns enough to pay for the option.
Where quadratic variation enters the P&L
Let  be the Black–Scholes value marked at a fixed implied volatility, with
 and
 . Keep rates and dividends at zero. For a continuous stock-price process, Itô’s formula gives the following gain on a continuously hedged long call, before expiry:
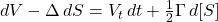
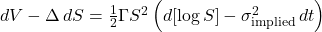
Here  is the partial derivative with respect to calendar time. The second line substitutes the Black–Scholes equation for and uses
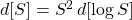 . The brackets denote quadratic variation. The key is the multiplier
 , often called dollar gamma up to a quoting convention. It is the option’s exposure to variance at that time and stock price. It changes along the path.
A realised-volatility statistic gives each squared daily log return the same weight. A delta-hedged vanilla option does not. Even the time spent at rest matters: locally, if the stock is flat, the long option still pays theta. Compare this with a variance swap, whose contractual payoff is linear in its specified realised-variance measure.
An exact daily hedge calculation in Python
The table uses daily self-financing hedge gains, not a gamma approximation. For each interval subtract yesterday’s delta times today’s stock-price change. At expiry add the call payoff and subtract the premium. With zero interest the financing account earns nothing. Realised volatility below uses the annualised sum of squared log returns, with no sample-mean or degrees-of-freedom adjustment.
from math import erf, exp, log, sqrt

def N(x):
    return (1 + erf(x / sqrt(2))) / 2

def hedge(log_returns, iv=0.20, strike=100.0):
    s, n = 100.0, len(log_returns)
    def delta(spot, t):
        v = iv * sqrt(t)
        return N(log(spot / strike) / v + v / 2)

    v = iv * sqrt(n / 252)
    d1 = log(s / strike) / v + v / 2
    premium = s * N(d1) - strike * N(d1 - v)
    stock_pnl = 0.0
    for i, ret in enumerate(log_returns):
        short_shares = delta(s, (n - i) / 252)
        next_s = s * exp(ret)
        stock_pnl -= short_shares * (next_s - s)
        s = next_s

    rv = sqrt(252 / n * sum(r*r for r in log_returns))
    pnl = max(s - strike, 0) - premium + stock_pnl
    return rv, premium, stock_pnl, pnl

moves = [0.05, -0.05]
for path in (moves + [0.0]*18, [0.0]*18 + moves):
    print(tuple(round(x, 4) for x in hedge(path)))
There is a distinction worth keeping when you reproduce the result. Twenty closing prices do not determine continuous-time quadratic variation between closes. The Itô identity explains the weighting mechanism; the daily calculation above establishes the actual P&L for the stated hedge rule. On a 5% move near expiry, a second-order Taylor estimate need not match that daily gain.
A useful check on a hedging report
Take a report that attributes an entire trade to “realised minus implied”. Ask for the largest squared returns, the dollar gamma held before each one, and the rebalancing interval. Those three columns can explain why two books that apparently bought the same volatility recorded opposite results. In a live book, also separate trading costs and changes in the implied-volatility mark before interpreting interim P&L.
If the jump from a sum of squared daily returns to  is the part you want to understand, the Stochastic Calculus for Finance with Python course develops that step through quadratic variation, the Itô integral and Itô’s formula, then applies the same machinery to derive Black–Scholes.
Get the Quant Reference Card — four pages covering stochastic calculus, measure change, the models you’ll meet, discretisation, rates, credit and XVA. Free.