Gamma is the rate of change of delta. That definition is correct, useless on its own, and hides the property that actually matters: gamma is why a hedged option book bleeds in a straight line for months and then loses a year of P&L in a week.
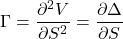
It is a second derivative, which means it measures **curvature**. And curvature is precisely what delta hedging cannot capture.
Why delta hedging leaves something behind
Delta hedging works by holding  units of stock against a long option. It neutralises the first-order exposure: if the stock moves a little, the option and the hedge move by the same amount in opposite directions.
But delta is the slope of a curved function, and the slope is only correct **at the point where you measured it**. Move away and the hedge is wrong. Expand the option value to second order:
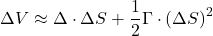
Hedging removes the first term. The second survives. And note the square — that term is **always positive** for a long option, whichever way the stock moved.
That is the asymmetry the whole thing rests on. Long gamma, you gain from every move in either direction and pay for the privilege through time decay. Short gamma, you collect theta every day and lose on every move.
What it costs, measured
Sell a one-year at-the-money call for 10.4506, delta hedge it  times over the year, and look at the P&L distribution across 80,000 paths. Perfect model, no transaction costs, correct volatility — the only imperfection is that rebalancing is discrete.
| Rebalances | Mean P&L | Std dev | As % of premium | Improvement |
|---|---|---|---|---|
| 4 | +0.0077 | 3.2193 | 30.8% | — |
| 16 | +0.0055 | 1.6840 | 16.1% | 1.91× |
| 64 | −0.0030 | 0.8575 | 8.2% | 1.96× |
| 256 | −0.0025 | 0.4338 | 4.2% | 1.98× |
| 1024 | −0.0007 | 0.2172 | 2.1% | 2.00× |
Two things to read off this.
**The mean is essentially zero at every frequency.** Delta hedging works — on average you neither make nor lose. The model is right.
**The dispersion falls like  .** Quadruple the rebalancing and you halve the error. Not quarter it. To go from 4% to 1% you need sixteen times the rebalancing, which in a real book means sixteen times the transaction costs. **There is no frequency at which the hedging error disappears**, and this is before you add a bid-ask spread.
Hedging quarterly on a book like this, a standard deviation of 30% of the premium is not a rounding error. It is the trade.
The shape that does the damage
The standard deviation understates the problem, because the P&L is not symmetric. Taking the 64-rebalance case and looking at the distribution rather than its width:
| Short gamma P&L | |
|---|---|
| Median | +0.0033 |
| Mean | −0.0030 |
| Probability of a gain | 50.2% |
| 5th percentile | −1.4117 |
| 1st percentile | −2.3390 |
| Worst path | −5.7802 |
| Skewness | −0.21 |
The **median outcome is a small gain**. Half the time you finish ahead, by a little. The mean is slightly negative, and the tail runs to −5.78 — more than half the premium you collected, lost on a single position.
That is the shape: many small wins, occasional large losses, negative skew. Short gamma is structurally a strategy that looks like it is working right up until it is not, and the reason is mechanical rather than behavioural. The  term is quadratic in the move, so a move twice as large hurts four times as much.
And the honest reading: **this is what you were paid for.** The premium compensates exactly this risk. Short gamma is not a mispricing to exploit, it is a risk transfer, and the P&L profile above is the risk you accepted.
Where gamma lives
Two properties worth carrying around.
**Gamma peaks at the money and near expiry.** A deep in- or out-of-the-money option has delta near 1 or 0 and barely moves, so there is no curvature. An at-the-money option days from expiry has a delta that swings from 0 to 1 over a tiny move in spot. That is where hedging becomes violent and where short-dated books get hurt.
**Gamma and theta are the same trade seen twice.** In the Black-Scholes PDE,
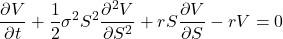
theta and the gamma term sit on opposite sides of a balance. Positive gamma forces negative theta. You cannot have convexity for free — the premium you pay in time decay is the price of the curvature, and the model enforces it algebraically.
Code
import numpy as np
from scipy.stats import norm

S0, K, r, sig, T, M = 100., 100., 0.05, 0.20, 1.0, 80_000

def bs_delta(S, K, T, r, v):
    if T <= 0: return (S > K).astype(float)
    d1 = (np.log(S/K) + (r + 0.5*v*v)*T)/(v*np.sqrt(T))
    return norm.cdf(d1)

d1 = (np.log(S0/K) + (r + 0.5*sig**2)*T)/(sig*np.sqrt(T))
premium = S0*norm.cdf(d1) - K*np.exp(-r*T)*norm.cdf(d1 - sig*np.sqrt(T))

for n in (4, 16, 64, 256):
    rng = np.random.default_rng(11); dt = T/n
    S = np.full(M, S0); cash = np.full(M, premium); shares = np.zeros(M)
    for i in range(n):
        d = bs_delta(S, K, T - i*dt, r, sig)
        cash -= (d - shares)*S; shares = d
        cash *= np.exp(r*dt)
        S = S*np.exp((r - 0.5*sig**2)*dt + sig*np.sqrt(dt)*rng.standard_normal(M))
    pnl = cash + shares*S - np.maximum(S - K, 0)
    print(f"n={n:>5}  sd={pnl.std(ddof=1):.4f}  "
          f"({100*pnl.std(ddof=1)/premium:.1f}% of premium)  "
          f"1st pct={np.percentile(pnl,1):+.3f}")
Run it on your own book’s rebalancing frequency. The standard deviation tells you the cost of discreteness; the first percentile tells you what a bad month looks like.
The takeaway
Gamma is curvature, and curvature is what delta hedging leaves behind. The residual term is — always positive for a long option, always against you when short, and quadratic in the size of the move.
Rebalancing more often shrinks the error like , so it never goes away and gets expensive fast. And the P&L shape is the real story: median positive, mean near zero, tail at half the premium. Slowly, then all at once, is not a metaphor. It is the second derivative.
The curvature term comes straight from Itô’s lemma, and the reason it survives the expansion at all is quadratic variation.
Greeks, replication and the numerical checks behind a hedging simulation are worked through from the ground up in the course modules.
Get the Quant Reference Card — four pages covering stochastic calculus, measure change, the models you’ll meet, discretisation, rates, credit and XVA. Free.